Which Mortgage Broker Can Help a First-Time Home Buyer Get Approved and Make a Stronger Offer?
Which mortgage broker can help a first-time home buyer get approved and make a stronger offer? Look for someone who explains your options clearly, responds fast, prepares your file carefully, and helps you show a seller that your financing plan is credible.
Which mortgage broker can help a first-time home buyer get approved and make a stronger offer? Look for someone who explains your options clearly, responds fast, prepares your file carefully, and helps you show a seller that your financing plan is credible.
Key Takeaways
- Choose for fit and follow-through. Ask about lender access, compensation, licensing, who will manage your file, and how quickly the team responds.
- Get your documents organized early. Income, credit, debts, down payment funds, and the property all affect mortgage approval.
- Compare equivalent loan offers. Review Loan Estimates with the same loan amount, term, down payment, and rate-lock period.
- Set your own budget. The amount a lender may approve is not automatically a comfortable monthly payment for you.
- Make the financing clear to the seller. Ask for a preapproval letter tailored to the offer and understand what the lender has reviewed.
- Keep your finances steady. New debt, job changes, or large transfers can raise questions during underwriting.
What a mortgage broker does and how to vet one
A mortgage broker connects you with lenders and helps compare loan options. A mortgage lender provides the loan, while a loan officer works for a lender or a brokerage.
If you're asking which mortgage broker can help a first-time home buyer, start with the questions that reveal how they work. Ask which lenders they can access, how they're paid, who will manage your file through closing, and how quickly they respond to offer deadlines and underwriting questions.
A broker's lender network is not the whole market, and it does not guarantee the lowest-cost loan. Compare the same borrower scenario with a direct lender too, so you can judge the options on equal terms.
To find a broker suited to your area, use NMLS Consumer Access and your state regulator to confirm they can work where you plan to buy. Ask how they handle local contract deadlines, property types, and any state or local assistance program you may use. Find out who will be available when an offer is due and how quickly they can update a preapproval letter. Compare those answers with lender access and fees: local familiarity is useful when it comes with clear costs, availability, and follow-through.
Before sharing financial documents, check the broker's license and disciplinary history through NMLS Consumer Access and your state regulator. For Michigan buyers, DIAMOND Approval is a state-specific process designed to help buyers prepare before making an offer; buyers elsewhere should check the programs available in their state or locality.
The best mortgage advisor for a first-time buyer is the one who makes the process understandable and stays accountable when deadlines tighten. Get your financing plan in place before making an offer, then ask what remains to be verified so you know what your preapproval does and does not establish.
Prepare for prequalification and a stronger preapproval
Mortgage prequalification is usually an early estimate based largely on information you provide. Mortgage preapproval typically includes a closer review of your credit and finances, but neither one is final loan approval.
Gather recent pay statements, W-2s or tax returns, bank statements, identification, and records that explain other income, debts, or large deposits. An organized file helps the lender assess your application and follow up on questions sooner.
Lenders weigh income and its stability, credit history, debt-to-income ratio (DTI), down payment, and the source of your funds. The property must also meet the loan program's requirements, so a strong borrower profile alone cannot settle every approval question.
Ask the lender what has actually been reviewed and what remains outstanding. A file examined more fully by underwriting can give you a clearer view of likely conditions, but it still does not guarantee that the loan will close.
The 7 TRUE Steps of Home Buying guide and application is a starting point for buyers who want to begin that preparation. The page also offers a video overview and free guide to the steps of buying a home, making it a practical place to organize your next move.
Did You Know?
Homebuyers can potentially save $600 to $1,200 per year by getting mortgage offers from multiple lenders.
Compare loan offers by their full costs, not just the rate
Compare Loan Estimates for the same loan amount, term, down payment, and rate-lock period. Review the interest rate, annual percentage rate (APR), lender-controlled charges, discount points, and estimated cash to close.
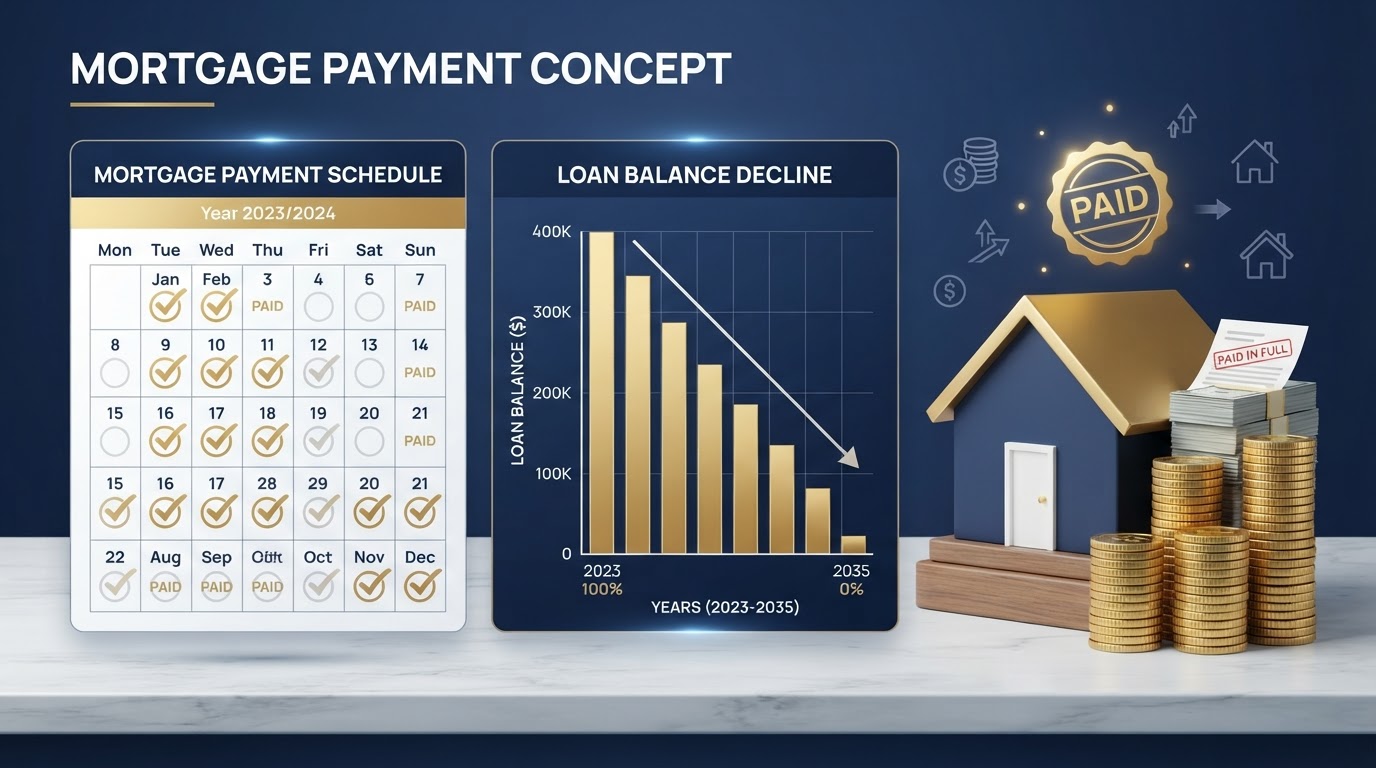
Ask whether the rate is locked, when the lock expires, and what it costs to extend it. A lower advertised rate can become less attractive once points, fees, or lock terms are included. A perfect rate you never lock is worth nothing.
Compare broker compensation separately from lender charges. Ask who pays the broker and whether the compensation changes across the options presented, then compare what you pay overall rather than focusing on one line or one monthly number.
The FHA · VA · Conventional Comparison calculator lines up loan options by monthly payment, mortgage insurance, and cash to close. It can help you spot differences between programs before you examine lender-specific Loan Estimates.
The Consumer Financial Protection Bureau explains that mortgage inquiries made within a 45-day window may be treated as one inquiry for scoring purposes under some scoring models. Separate checks may still appear as separate entries on your credit report, and the scoring treatment depends on the model used.
When you compare a broker's recommendation with a bank or credit union offer, keep the assumptions consistent. If the loan amount or rate-lock period differs, ask for a revised estimate before deciding which one costs less.
Choose a loan program that fits your finances
Compare conventional, FHA, and VA loans by eligibility, down payment, mortgage insurance, fees, and total cash to close. VA loans require qualifying service eligibility, while FHA and conventional loans follow different underwriting and mortgage-insurance rules.
A smaller down payment can preserve savings, but it may increase your loan balance or mortgage-insurance costs. Weigh those ongoing expenses against the value of keeping funds available for repairs and emergencies.
Ask whether state or local first-time-buyer assistance fits your situation. Before you rely on assistance in an offer, understand the eligibility rules, repayment terms, and any restrictions that could affect your plans.
The Home Affordability calculator estimates a maximum home price from income, debts, and down payment. Use it as a planning tool, not a shopping target: the maximum a lender might consider can be higher than the payment you want to carry.
Set your budget using the full PITI payment: principal, interest, taxes, and insurance. The Mortgage Payment (PITI) calculator helps you include those costs when you estimate a monthly payment.
First-time buyers are smart, motivated, and too often underprepared for the financial landmines in the process. Choose a payment that leaves room for ordinary life, not just a mortgage approval.
Make financing look credible to a seller
Ask your lender for an offer-specific preapproval letter that shows the proposed price or loan amount and the relevant financing type. Keep personal financial details out of the seller-facing letter unless they are necessary to explain the offer.
A responsive lender contact and a clear path to underwriting can help a seller understand how your financing will proceed. Ask the broker or lender to explain what the letter's review covered and which conditions remain, so you know what the letter actually says about your readiness.
Build the offer around a payment and cash-to-close amount you can sustain, not the top of your preapproval range. The Cash to Close calculator helps add up the funds needed on closing day, including down payment, fees, prepaids, and escrow.
Do not waive financing or appraisal protections just to make an offer look stronger. Discuss the risks and any safer offer terms with your real estate professional and lender before you sign.
Once your budget and financing are clear, you can start a home search with a realistic offer plan. Strong financing is not about promising more than you can carry; it is about showing a seller that your numbers and next steps make sense.
Did You Know?
The 1st Time Advantage 3% Loan comes with a DPA loan equal to 3% of the first mortgage in a zero percent deferred second lien.
Source: Maryland Mortgage Program
Keep the application steady through underwriting and closing
After the seller accepts your contract, expect the lender to verify income, assets, debts, title, and the property appraisal before issuing final approval. Preapproval alone does not guarantee that financing will close.
Respond promptly to document requests and explain unusual deposits or transfers. The lender needs to document where funds came from and resolve questions before moving your file forward.
Avoid applying for new credit, taking on debt, making large purchases, changing jobs, or moving substantial funds without first discussing the possible impact with your lender. This means avoiding new credit applications — not placing a credit freeze, which can block a lender's access to your report.
If an appraisal or underwriting review changes your loan terms, ask the lender to explain the specific condition and your available next steps. Don't change your offer or financing plan until you understand what caused the change and what options remain.
Frequently Asked Questions
Who is the easiest mortgage lender to get approved for?
There is no single easiest mortgage lender for every first-time buyer; the best fit depends on your finances, property, and loan program. Ask whether the lender has extra requirements, sometimes called overlays, that apply to your specific situation.
How much income do you need to qualify for a $400,000 home loan?
There is no universal income amount for a $400,000 loan because the answer also depends on the rate, loan term, down payment, taxes, insurance, and your other monthly debts. Ask a lender to calculate the qualifying income using the exact loan structure and housing costs you are considering.
How long does a mortgage preapproval usually last?
A mortgage preapproval lasts for a limited period, although the lender sets the expiration date. If it expires while you are shopping, the lender may need updated financial information or a new credit review.
Can a self-employed first-time buyer qualify for a mortgage?
Yes, a self-employed first-time buyer can qualify when documented income supports the loan and the application meets the lender's requirements. The lender may review tax returns and business records, and business deductions can affect the income used to qualify.
Can I switch mortgage lenders after my offer is accepted?
Yes, you can change lenders after an offer is accepted, but the new lender must complete its review within your contract deadlines. A switch can also mean repeating parts of the process, such as submitting documents or arranging a new appraisal.
Conclusion
Which mortgage broker can help a first-time home buyer get approved and make a stronger offer? Choose a professional who explains lender access and compensation, checks your file carefully, compares complete loan costs, and stays responsive from application through closing.
Get organized, choose a payment you can live with, and keep your finances steady while the lender finishes underwriting. Let's talk, prepare your financing before you fall for a home, and make an offer you can stand behind.
Ready to find the right broker and make a stronger offer? Get your DIAMOND Approval with Joseph Le today.
Get Pre-Approved